If you’ve seen headlines about ISAs being “cut” and felt a small knot of worry, you’re not alone. The good news is that the change is smaller than it sounds, it doesn’t touch money you’ve already saved, and you have until next April to make the most of the current rules.
Here’s what’s actually happening, in plain English.
What’s changing
The overall ISA allowance is staying at £20,000 a year. What changes is how much of it can go into cash. From 6 April 2027, savers under 65 will be able to put a maximum of £12,000 a year into Cash ISAs. The change was announced in the Autumn Budget 2025.
In other words, you can still put £20,000 a year into ISAs. The difference is that, if you’re under 65, no more than £12,000 of it can be in cash. To use the rest, you’d need another type of ISA, such as a Stocks and Shares ISA.
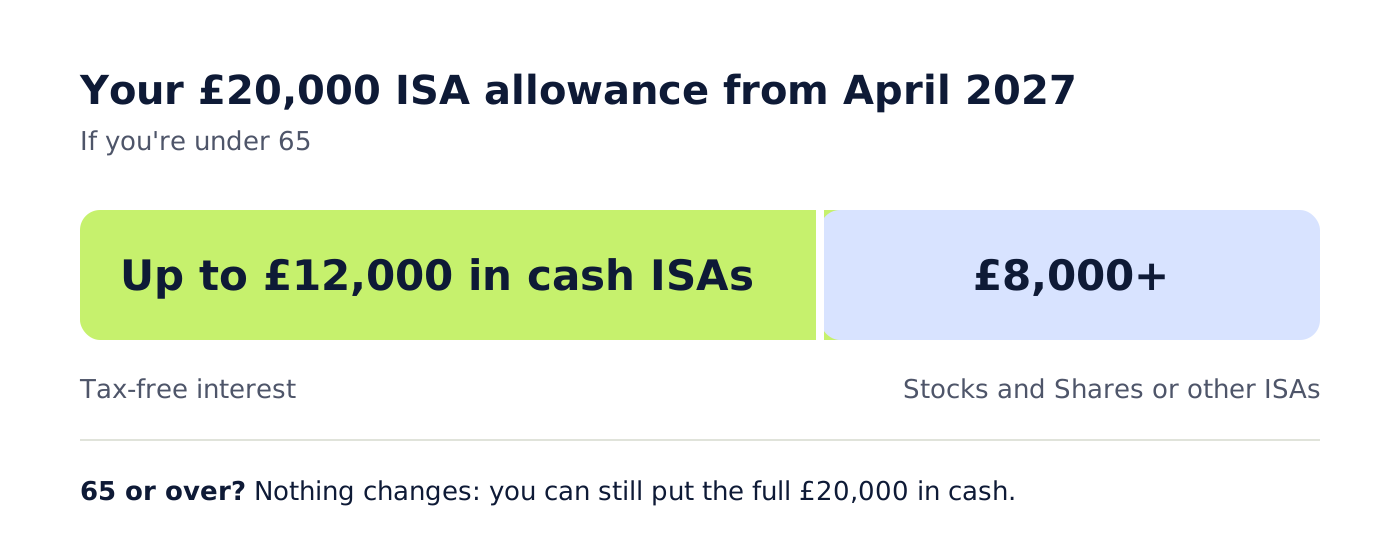
Good to know: If you’re 65 or over, nothing changes. Your Cash ISA limit stays at £20,000.
What it doesn’t change
- Money already saved is safe. The new limit only applies to money paid in from 6 April 2027. Existing Cash ISA balances aren’t affected, and nobody will make you move them.
- If you save less than £12,000 a year in cash, nothing changes in practice. Most households never get near the limit. If that’s you, carry on as you are.
Who should pay attention
The change matters if you’re under 65 and one of these applies:
- You regularly put more than £12,000 a year into Cash ISAs
- You have a lump sum coming, such as a bonus, inheritance or house sale, that you’d planned to keep in cash
- You’ve been meaning to “sort out your ISA” for a while and keep putting it off
This tax year, which ends on 5 April 2027, is the last one in which under-65s can put the full £20,000 into Cash ISAs.
Cash ISA vs Stocks and Shares ISA
| Cash ISA | Stocks and Shares ISA | |
|---|---|---|
| Risk | Low: your balance won’t fall | Higher: values go up and down |
| Returns | Interest, tax-free | Investment growth, tax-free |
| Best for | Money you may need within a few years | Money you can leave for 5+ years |
| From April 2027 | Up to £12,000 a year (under 65) | Up to £20,000 a year |
What to do this tax year
- Keep your emergency fund in cash, always. Money you might need at short notice belongs in an easy-access account, not the stock market. If you don’t have a buffer yet, start there.
- If you have cash savings you won’t need soon, consider using your full Cash ISA allowance before April. Interest in an ISA is tax-free, and anything you pay in before 6 April 2027 keeps that protection for as long as you leave it there.
- If you’re saving for 5+ years, look at a Stocks and Shares ISA. Over long periods, investing has historically beaten cash, but your investments can fall as well as rise, and you may get back less than you put in.
- Transfer, don’t withdraw. To switch providers, use the new provider’s ISA transfer service. Taking the money out yourself and paying it back in can use up your allowance.
The short version
The overall £20,000 ISA allowance isn’t changing. From April 2027, under-65s can put a maximum of £12,000 a year into cash ISAs. Existing savings aren’t affected. If you normally save more than £12,000 a year in cash, this tax year is your last chance to shelter the full £20,000 in cash.
Common questions
Will this affect the money already in my Cash ISA?
No. The new limit only applies to money paid in from 6 April 2027. Existing balances stay where they are and keep their tax-free status.
I'm 65 or over. Does this apply to me?
No. If you're 65 or over, your Cash ISA limit stays at £20,000 a year.
Can I have more than one Cash ISA?
Yes. Since April 2024 you can pay into more than one ISA of the same type in a tax year, as long as your total stays within your allowance.
What happens if I don't use my allowance?
It's lost. Any allowance you don't use by 5 April can't be carried over to the next tax year.
This article is general information, not personal financial advice. Your situation is your own, so check the details for yourself or speak to a regulated adviser before making big decisions. Where investments are mentioned, their value can go down as well as up.